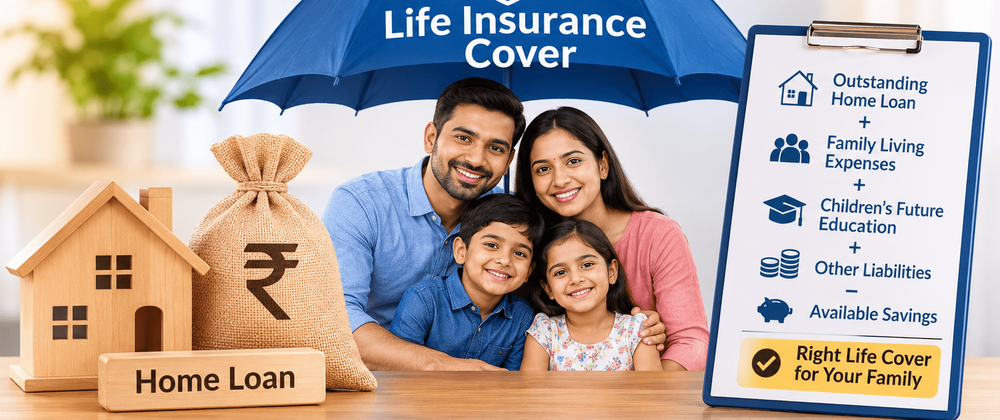

A home loan can remain a major financial responsibility for 15, 20 or even 30 years. If the primary earning member passes away while the loan is outstanding, the family may have to manage the repayments alongside regular household expenses.
Understanding why life insurance is important becomes particularly relevant when a family takes on a long-term financial commitment such as a home loan. The required cover should not be limited to the outstanding loan. It should also account for dependants' living costs, future goals and existing financial resources. A clear calculation can help families choose suitable protection without paying for unnecessary cover.
Why is life insurance important after taking a home loan?
A home loan creates a financial commitment that continues for several years. If the borrower is no longer able to provide income, the family may have to use savings or other assets to continue paying the equated monthly instalments (EMIs).
Life insurance can help address this risk by providing financial support to the nominee if the life insured passes away during the policy term, subject to the policy conditions. The payout can help repay the outstanding loan, meet household expenses or support future financial goals.
For example, consider a family with a home loan of Rs. 40 lakh and two dependent children. If the earning member passes away while the loan is active, the family may need funds to manage both the loan repayments and expenses such as education, healthcare and daily living costs.
Covering only the outstanding loan may not provide sufficient financial support. This is why families should consider their overall financial responsibilities when estimating their life insurance requirements.
How much life insurance cover should a family consider?
There is no fixed life insurance amount for every home loan borrower. A practical starting point is to add the outstanding loan to the family's future financial requirements and deduct the financial resources already available to meet those needs.
Consider this example:
- Outstanding home loan: Rs. 40 lakh
- Estimated family living expenses: Rs. 30 lakh
- Children's future education expenses: Rs. 20 lakh
- Other outstanding liabilities: Rs. 5 lakh
- Existing savings and investments available for these needs: Rs. 15 lakh
The estimated life cover requirement would be:
Required cover = Home loan + Family expenses + Future goals + Other liabilities − Available financial resources
Rs. 40 lakh + Rs. 30 lakh + Rs. 20 lakh + Rs. 5 lakh − Rs. 15 lakh = Rs. 80 lakh
In this example, the family may consider life cover of around Rs. 80 lakh as a starting estimate.
However, the final amount should also account for inflation, future income requirements and other sources of financial support. Families should avoid deducting assets that are already set aside for essential expenses or long-term goals.
Should you choose home loan protection or a regular term policy?
Borrowers may come across two broad types of life cover when taking a home loan. Both offer financial protection, but their coverage and payout arrangements can differ.
- Home loan protection cover
- Designed to help repay the outstanding home loan if the covered borrower passes away during the policy term.
- The sum assured generally decreases over time in a reducing cover structure, broadly following the loan balance.
- Depending on the policy and assignment arrangements, the lender may receive the amount required to settle the outstanding loan.
- Some policies may have a single premium or a limited premium payment period.
- Individual term insurance
- Provides life cover for a selected amount and policy term.
- The sum assured may remain unchanged throughout the policy term under a level cover structure.
- The nominee generally receives the applicable payout, subject to the policy conditions and any assignment.
- The family can use the payout to repay the home loan and meet other financial responsibilities.
A reducing cover may broadly follow the loan balance, while an individual term policy can provide protection for wider family needs.
Before choosing, check what happens if you repay the loan early, transfer it to another lender or close it before the policy ends. Also understand who receives the payout and whether the cover can continue independently of the loan.
What should you check before buying digital life insurance?
Digital life insurance allows applicants to research policies, compare features, submit applications and access policy documents online. While this makes the process more convenient, the policy terms still need careful review.
Consider these points before purchasing:
- Sum assured: Check whether the cover is sufficient for the outstanding loan and the family's other financial needs.
- Policy term: Choose a duration that reflects how long your family may depend on your income.
- Premium payment: Compare the total premium and payment duration rather than looking only at the monthly instalment.
- Payout structure: Understand whether the nominee receives a lump sum, instalments or another permitted payout option.
- Exclusions and disclosures: Read the policy conditions and provide accurate information about health, occupation, income and existing policies.
- Policy ownership: Check whether the policy is assigned to the lender and understand how this affects the nominee's rights.
When purchasing digital life insurance, use the insurer's official website or an authorised distribution channel. Keep copies of the policy schedule, premium receipts and application details for future reference.
Can a lender make life insurance compulsory with a home loan?
Borrowers should distinguish between a lender recommending insurance and requiring a specific policy purchase. IRDAI's 2024 Master Circular on Protection of Policyholders' Interests allows borrowers seeking insurance for housing or other loans to choose an insurer or authorised distribution channel.
In September 2026, IRDAI also proposed additional safeguards to prevent banks and non banking financial companies from compulsorily bundling insurance with their loans. These proposals were under consultation and should not be treated as final regulations.
If a lender offers a loan linked life insurance policy, consider these points before accepting it:
- Ask for a separate breakdown of the insurance premium.
- Check whether the premium is added to the home loan amount.
- Calculate the additional interest payable if the premium is financed through the loan.
- Compare the offered policy with independently purchased life insurance.
- Understand the claim process and the conditions for cancellation or continuation of cover.
Also remember that life insurance and property insurance serve different purposes. A lender may have separate requirements relating to insurance for the financed property. Property insurance protects the house against specified risks, while life insurance provides financial support to the family following the insured person's death.
Understanding these differences can help borrowers identify the cover they actually need.
Conclusion
A family taking a home loan should consider life insurance that addresses both the outstanding debt and its wider financial responsibilities. Calculate the required cover using the loan balance, dependants' needs, future expenses and available resources. Whether choosing home loan protection or individual term insurance, review the policy conditions, payout arrangements and costs carefully. Suitable life cover can help a family manage financial commitments if the earning member passes away during the policy term.



Top comments (0)