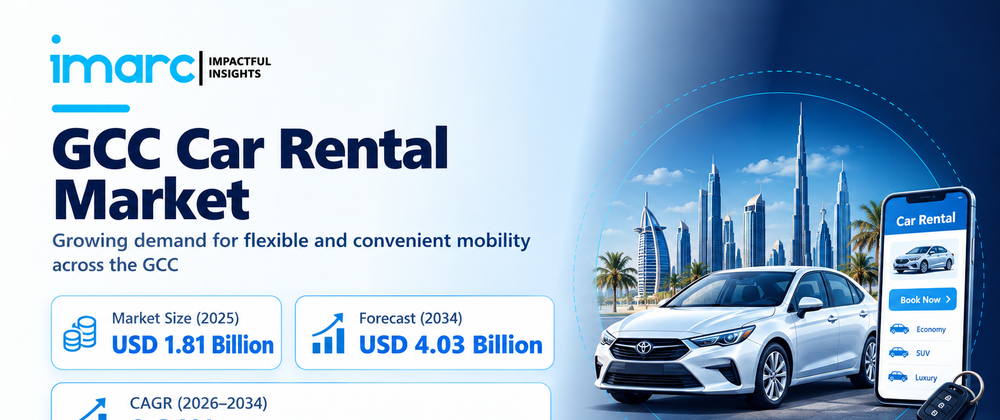

IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Car Rental Market. The GCC car rental market size reached USD 1.81 Billion in 2025 and is projected to reach USD 4.03 Billion by 2034, exhibiting a CAGR of 9.31% during 2026-2034. Surging inbound tourism, expanding expatriate populations, robust business travel demand and the rapid adoption of digital booking platforms are the primary growth catalysts.
Car rental is an essential part of mobility across the GCC, where public transit networks are still developing in several cities and visitors, expatriate workers and corporates all need flexible access to vehicles. Saudi Arabia is the region's largest market, supported by Vision 2030 tourism, year-round Hajj and Umrah travel and giga-project activity, while the UAE leads on revenue per rental day and is the most advanced market for digital booking and early electric vehicle fleets. At the same time, the industry is moving online, with app-based booking, digital contracts, telematics, AI-driven pricing and subscription products reshaping how operators win customers, and regulators such as Saudi Arabia's Transport General Authority tightening rules for rental and brokerage activity. The year 2026 has also been uneven, with regional conflict reducing travel into the UAE in the first half while Saudi rental contracts continued to grow, and operators have been expanding branch networks, platforms and fleets regardless. Combined with infrastructure investment and a growing push toward electric fleets, these forces are shaping a durable, long-term growth path across Saudi Arabia, the UAE, Qatar, Kuwait, Oman, and Bahrain.
GCC Car Rental Market at a Glance:
- Market Size (2025): USD 1.81 Billion
- Market Forecast (2034): USD 4.03 Billion
- Growth Rate (2026-2034): CAGR of 9.31%
- Base Year: 2025 | Historical Period: 2020-2025 | Forecast Period: 2026-2034
- Leading Booking Type: Online Booking, holding a 71.2% share in 2025, driven by high smartphone penetration and a preference for seamless digital experiences
- Leading Rental Length: Short Term, with a 66.3% share in 2025, serving tourists and business travelers on short stays
- Leading Country Market: Saudi Arabia, commanding a 42.6% share in 2025, driven by Vision 2030 tourism ambitions and the year-round Hajj and Umrah travel cycle
How AI is Reshaping the Future of the GCC Car Rental Market
- AI-Driven Dynamic Pricing and Predictive Fleet Management: According to the report, machine learning algorithms process seasonal tourism surges, corporate booking patterns, vehicle availability and competitor rates to generate dynamic pricing, while predictive maintenance and fleet optimization are now standard among top-tier operators, and Hertz has introduced AI-based dynamic pricing in the region.
- Telematics and Digital Contracts in Saudi Arabia: Saudi operators including Lumi, Theeb and Yelo are investing in telematics and branch networks, and the Transport General Authority issued more than 1.6 million car rental contracts in the first quarter of 2026, up 7% year on year, within a regulated electronic framework that it updated again in June 2026.
- Platform and Subscription Models: Legend Holding Group committed a fleet of 1,000 vehicles valued at more than USD 20 million to the Swapp platform in May 2026, linking fleet scale to platform distribution, while the report highlights super-app integration with Careem, Noon and stc pay and subscription services growing at an estimated 14% CAGR.
Grab a sample PDF of this report: https://www.imarcgroup.com/gcc-car-rental-market/requestsample
GCC Car Rental Market Trends and Drivers:
Demand for car rental across the GCC is being underpinned by tourism and religious travel. Saudi Arabia welcomed an estimated 122 million visitors in 2025 and targets 150 million a year by 2030, with Hajj and Umrah travel creating ground transport demand between Makkah, Madinah and Jeddah, while Dubai recorded 19.59 million international overnight visitors in 2025. Expatriates are another structural base, since frequent job-linked relocations generate sustained demand for monthly and long-term contracts, and the report notes that expatriates make up about 88% of the UAE population.
The market's structural differentiator is the shift to digital, regulated and platform-led rental. Online booking accounts for 71.2% of revenue, mobile apps allow real-time vehicle selection, digital identity checks and in-app payment, and in Saudi Arabia the Transport General Authority's rules for electronic contracts and brokerage applications are formalizing the market, with Lumi expanding to 44 locations across 20 cities in June 2026 and Theeb to 72 branches in July 2026. The picture is uneven, however, with regional conflict cutting UAE hotel occupancy by 27.7 percentage points in the first half of 2026 while Saudi rental contracts still grew 7% in the first quarter.
A third driver is electrification and subscription models. EV adoption in rental fleets remains below 5% of inventory in 2025 according to the report, but the Dubai Taxi Company added 250 EVs in 2024, Dubai's EV count reached 47,944 at the end of 2025 with 2,223 public charging points by the first quarter of 2026, and corporate fleet subscriptions are growing as giga-project and expatriate demand favors all-inclusive monthly plans. Operators also face fleet procurement costs, regulatory differences across the six GCC states and competition from ride-hailing, a dynamic that is set to intensify over the coming decade.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=11487&flag=E
Government Schemes and National Mobility Programs Driving Demand:
- Saudi Vision 2030 Tourism Targets: Saudi Arabia raised its ambition to 150 million visitors a year by 2030, comprising 70 million international and 80 million domestic tourists, after welcoming an estimated 122 million visitors in 2025, expanding the base of renters across airports, religious cities and tourist destinations.
- Transport General Authority Regulatory Framework: The TGA regulates private car rental and rental brokerage in Saudi Arabia, issued more than 1.6 million rental contracts in the first quarter of 2026, and in June 2026 approved further amendments to the executive regulation (Decision 9/2 TR/4/2026) following 2025 updates governing electronic brokerage applications.
- UAE Net Zero 2050 and Saudi Green Initiative: Climate programs are encouraging electric fleets, supported by Dubai's charging network of 2,223 public points by the first quarter of 2026 and by operators such as the Dubai Taxi Company adding EVs.
- Giga-Projects, Expo 2030 and the 2034 World Cup: Saudi Arabia's reprioritized giga-project pipeline, Expo 2030 Riyadh and the 2034 FIFA World Cup create long-term corporate leasing and subscription demand, with the report citing NEOM, the Red Sea Project and Diriyah Gate as demand centers.
- National Visions in Qatar and Oman: According to the report, Qatar targets 6 million annual visitors by 2030 and builds on its FIFA 2022 legacy infrastructure, while Oman Vision 2040 and an eco-tourism target of 11 million visitors by 2040 support self-drive rental demand.
GCC Car Rental Market Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Booking Type:
- Offline Booking
- Online Booking
Online booking dominates with a 71.2% share in 2025, driven by high smartphone penetration and consumer preference for seamless digital experiences, while offline booking holds 28.8%, serving airport walk-in customers, small businesses with negotiated contracts and travelers in lower-connectivity markets.
Breakup By Rental Length:
- Short Term
- Long Term
Short-term rentals dominate with a 66.3% share in 2025, reflecting tourist and transient business traveler demand, while long-term rentals of one month or more account for 33.7%, with corporate clients on giga-projects and expatriate households preferring subscription models over vehicle ownership.
Breakup By Vehicle Type:
- Luxury
- Executive
- Economy
- SUVs
- Others
SUVs lead the vehicle type segment with a 42.4% share in 2025, reflecting family, desert and long-distance travel needs, while luxury, executive and economy categories serve premium, corporate and budget demand.
Breakup By Application:
- Leisure/Tourism
- Business
Leisure and tourism leads with a 68.5% share in 2025, supported by inbound tourism and religious travel, while business use covers corporate travel, MICE activity and project teams.
Breakup By End-User:
- Self-Driven
- Chauffeur-Driven
Self-driven rentals lead with a 60.4% share in 2025, reflecting road-trip tourism and flexible expatriate mobility, while chauffeur-driven rentals serve executive, premium and event travel and face a skilled driver shortage according to the report.
Breakup By Country:
- Saudi Arabia
- UAE
- Qatar
- Kuwait
- Oman
- Bahrain
Saudi Arabia leads with a 42.6% share in 2025, followed by the UAE at 24.8%, Qatar at 10.6%, Kuwait at 8.7%, Oman at 7.1% and Bahrain at 6.2%. Saudi dominance reflects Hajj and Umrah travel and giga-projects, the UAE offers the highest revenue per rental day and strong corporate demand, Qatar benefits from post-2022 infrastructure, Kuwait from its large expatriate workforce, Oman from eco-tourism and Bahrain from cross-border demand over the King Fahd Causeway.
Competitive Landscape:
The GCC car rental market is moderately concentrated, with the leading operators competing on fleet size, digital platform capabilities, geographic coverage and premium service tiers. Key players include:
- Enterprise Holdings, Inc.
- The Hertz Corporation
- Sixt
- Budget Rent A Car
- Al Sulaiman Rent-A-Car
- Theeb Rent a Car
- Lumi Rental
- Yelo (Al Wefaq Transportation Solutions)
Global brands such as Enterprise, Hertz and Sixt anchor airport and corporate rental across the region, with Sixt focusing on digital-first and premium customers, Hertz on AI pricing and its Prestige Collection, and Enterprise on corporate accounts and long-term subscriptions. Saudi listed operators such as Budget Saudi, Lumi and Theeb, together with Yelo, lead their home market through branch networks, used-vehicle remarketing and telematics.
Market Concentration Analysis:
- The GCC car rental market is moderately concentrated, with the top operators, Enterprise, Hertz, Sixt, Budget, and Al Sulaiman, collectively accounting for an estimated 65-70% of total revenue in 2025, reflecting the capital intensity of fleet procurement, where a top-tier operator may hold 10,000 to 50,000 vehicles.
- Fragmentation is most evident at the city or country level, where dozens of independent operators compete for small business and tourist demand, and in Saudi Arabia, where the four listed players, Budget Saudi, Lumi, Theeb and Cherry, controlled 53% of industry revenues according to an Argaam sector report in February 2026, creating a structure where large operators lead corporate and airport demand while independents focus on local and price-led niches.
- Consolidation and platform partnerships are ongoing, with the report recording three significant M&A transactions involving GCC fleet operators between 2022 and 2024, Budget Saudi's acquisition of AutoWorld lifting its share, and Legend Holding Group's commitment of 1,000 vehicles to the Swapp platform in May 2026.
What Does The Full Report Cover?
- Historical, current, and forecast market size for the GCC car rental market from 2020 to 2034
- Market breakup by booking type, rental length, vehicle type, application, end-user, and country
- Country-level analysis covering Saudi Arabia, UAE, Qatar, Bahrain, Kuwait, and Oman
- Key growth drivers, restraints, challenges, and opportunities shaping the market
- Porter's Five Forces analysis and value chain assessment
- Competitive landscape, market structure, and player positioning
- Detailed profiles of major car rental companies in the GCC
Recent News and Developments in the GCC Car Rental Market
- July 2026: Theeb Rent a Car opened two new branches in Mahayil Aseer and Abha, expanding its nationwide network in Saudi Arabia to 72 branches.
- June 2026: The Transport General Authority approved further amendments to the Executive Regulation for private car rental and rental brokerage (Decision 9/2 TR/4/2026), reinforcing compliance requirements for licensing and contracting workflows, while Lumi added branches in Tabuk, Taif and Jeddah to reach 44 locations across 20 Saudi cities.
- May 2026: Legend Holding Group committed a fleet of 1,000 vehicles valued at more than USD 20 million to the Swapp platform, linking fleet scale to platform distribution.
- First Quarter 2026: Saudi Arabia's Transport General Authority issued more than 1.6 million car rental contracts, a 7% increase from the same period of 2025.
- February 2026: An Argaam sector report on Saudi car rentals found that the four listed players, Budget Saudi, Lumi, Theeb and Cherry, collectively control 53% of industry revenues, with Budget Saudi leading on scale and Lumi offering digital-first exposure.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- How big is the GCC car rental market and what is its growth outlook through 2034?
- What are the major growth drivers, restraints, and opportunities in the GCC car rental market?
- Which booking type, rental length, vehicle type, and country hold the largest share of the market?
- Which country leads the GCC car rental market, and why?
- How are digital booking, telematics, and AI-driven pricing reshaping the industry?
- Who are the key players in the GCC car rental market, and how is the competitive landscape evolving?
- What role are electric fleets, subscriptions, and mobility platforms playing in the future of the market?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104




Top comments (0)