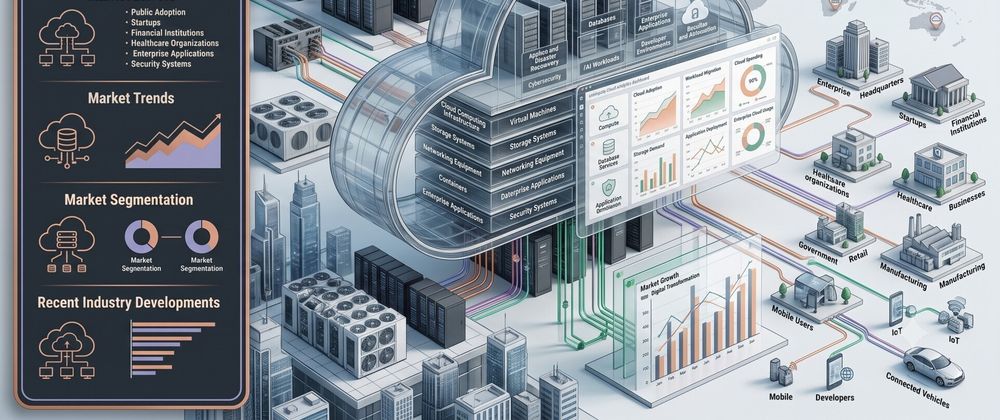

IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the public cloud market. The global public cloud market size reached USD 1,017.5 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 4,499.2 Billion by 2034, exhibiting a growth rate (CAGR) of 17.42% during 2026-2034, driven by the growing need for cost-effective IT solutions, rising focus on scalability to reduce the risk of downtime, increasing demand for solutions suited to remote and hybrid work settings, and expanding adoption of AI, edge computing, and IoT workloads across industries worldwide. North America accounts for the largest regional share.
The market is experiencing strong momentum as organizations shift away from capital-intensive on-premises infrastructure toward flexible, pay-as-you-go consumption models. Startups and small businesses gain access to enterprise-grade computing without upfront investment, while large enterprises use public cloud platforms to scale workloads, optimize IT spending, and modernize legacy applications. Hyperscalers are operating geographically distributed networks of data centers that deliver low-latency access to users regardless of location, and providers are layering AI services, industry-specific compliance certifications, and enhanced security on top of core infrastructure. Simultaneously, governments are treating cloud capacity as strategic infrastructure, funding sovereign compute, streamlining procurement, and encouraging domestic data center build-outs.
How AI is Reshaping the Future of the Public Cloud Market
-
AI Infrastructure Demand Is Rewriting Cloud Capacity Planning: Training and running AI models is now the single largest driver of new public cloud capacity. Amazon raised its capital expenditure guidance to approximately USD 220 Billion, while Alphabet lifted its guidance to a range of USD 195 Billion to USD 205 Billion, and executives across the leading hyperscalers report that demand continues to exceed available supply.
-
Sovereign and Shared AI Compute Through Public-Private Cloud Partnerships: Governments are using public cloud providers to democratize access to expensive GPU capacity. India's IndiaAI Mission has built a common compute pool of more than 38,000 GPUs through empanelled cloud service providers, with subsidized access for startups, researchers, and academia at roughly INR 65 per hour, and has selected domestic firms to build indigenous foundation models.
-
AI-Enabled Public Sector and Enterprise Adoption at Scale: Cloud platforms are becoming the delivery channel for generative AI across large institutions. The United States General Services Administration's agreement with Microsoft covers Azure, Microsoft 365, and Copilot for federal agencies with potential first-year savings of USD 3.1 Billion, illustrating how bundled cloud and AI offerings are reshaping procurement and accelerating deployment across regulated environments.
Grab a sample PDF of this report: https://www.imarcgroup.com/public-cloud-market/requestsample
Public Cloud Market Trends and Drivers:
The global public cloud market is witnessing sustained expansion, fueled by the convergence of cost optimization, workload scalability, and the rapid mainstreaming of AI-driven applications. Companies increasingly favor consumption-based pricing over heavy capital investment in servers and data centers, a shift that benefits startups with limited capital and allows larger enterprises to align IT spending with actual usage. According to Thales Group, over 60% of all business data is now stored in the cloud, a share that has more than doubled from 30% in the past. The scale of the leading platforms illustrates the momentum, with Microsoft Azure surpassing USD 100 Billion in annual revenue and growing 43% in its latest quarter, while Amazon Web Services reported quarterly revenue of USD 42.2 Billion, up 37%, its fastest expansion in 18 quarters.
Sovereignty, regulation, and public investment are reshaping where and how public cloud capacity is built, creating a structural differentiator across regions. In the European Union, the InvestAI initiative aims to mobilize EUR 200 Billion for AI investment, including EUR 20 Billion for up to five AI gigafactories equipped with around 100,000 advanced chips, while the proposed Cloud and AI Development Act targets at least tripling EU data center capacity within five to seven years. In India, the IndiaAI Mission carries an outlay of INR 10,372 Crore, and global hyperscalers have responded with large commitments, including Microsoft's USD 17.5 Billion over four years and Google's USD 15 Billion for an AI hub in Visakhapatnam. In the United States, the General Services Administration's OneGov program has generated USD 800 Million in governmentwide savings and includes an Amazon Web Services arrangement offering up to USD 1 Billion in incentive credits for migration, modernization, and training across federal agencies.
Remote work, global reach, and dealmaking activity are reinforcing adoption across enterprises of every size. Public cloud allows employees to access data and applications from anywhere, and a Flexera survey indicates that 75% of enterprise respondents use Microsoft Azure for public cloud, while AWS, Microsoft Azure, and Google Cloud operate distributed data center networks that place applications close to end users. Demand visibility remains exceptionally strong, with AWS reporting a backlog of USD 496 Billion and Microsoft reporting commercial remaining performance obligations of USD 678 Billion, even as the market faces a persistent shortage of skilled cloud professionals. Providers are also pursuing partnerships, acquisitions, and industry-specific offerings to broaden their portfolios, setting up a more regulated and sovereignty-conscious competitive environment.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=7071&flag=E
Public Cloud Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Service:
- Infrastructure as a Service (IaaS)
- Platform as a Service (PaaS)
- Software as a Service (SaaS)
Software as a Service accounts for the largest service segment, driven by the subscription-based delivery of applications that are hosted and maintained by the cloud provider and accessed through web browsers. Companies are increasingly investing in SaaS for productivity, collaboration, security, and customer engagement, and providers are launching in-region services to meet data sovereignty requirements, as seen when Aqua Security made its cloud-native security SaaS generally available in Singapore to serve government, banking, and financial services customers across the Asia Pacific region.
Breakup By Enterprise Size:
- Large Enterprise
- Small and Medium-sized Enterprises
Small and medium-sized enterprises hold the largest market share, attracted by the cost-effectiveness, scalability, and access to advanced technology without significant upfront investment. Subscription-based pricing gives SMEs the flexibility to grow at their own pace, and they typically rely on SaaS solutions for productivity and collaboration alongside basic infrastructure needs such as web hosting and data storage.
Breakup By End Use:
- BFSI
- IT and Telecom
- Retail and Consumer Goods
- Manufacturing
- Energy and Utilities
- Healthcare
- Media and Entertainment
- Government and Public Sector
- Others
BFSI represents the leading end use segment, leveraging public cloud services for data analytics, risk management, fraud detection, and customer relationship management while responding quickly to market dynamics and regulatory changes. Providers are tailoring offerings for the sector, exemplified by Kyndryl's launch of new services that help financial institutions store and protect confidential data on Google Cloud with a unified, scalable, and security-rich data platform that supports regulatory and compliance requirements.
Breakup By Region:
- North America (United States, Canada)
- Europe (Germany, France, United Kingdom, Italy, Spain, Others)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
North America leads the global public cloud market with the largest regional share, supported by a robust digital infrastructure, a mature IT ecosystem, and the presence of major vendors such as Microsoft, Oracle, Amazon, and IBM. It is estimated that more than 50% of government organizations in the United States have deployed cloud services, and 18% of North American respondents in one industry survey report a monthly cloud spend between USD 100,000 and USD 250,000, underscoring the depth of enterprise investment across the region.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the public cloud market with detailed profiles of all major companies, including:
- Alibaba Group Holding Limited
- Amazon Web Services Inc.
- Cisco Systems, Inc.
- Google LLC (Alphabet Inc.)
- Hewlett Packard Enterprise Development LP
- International Business Machines Corporation
- Microsoft Corporation
- Oracle Corporation
- Rackspace Technology Inc.
What Does The Full Report Cover?
If you are tracking the public cloud market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
- Complete market sizing with revenue forecasts covering the full projection period
- Quantified growth driver analysis across service, enterprise size, end use, and regional markets
- Sub-segment breakdowns for IaaS, PaaS, SaaS, large enterprises, SMEs, BFSI, IT and telecom, retail and consumer goods, manufacturing, energy and utilities, healthcare, media and entertainment, and government and public sector with individual share data
- Country-level data for the United States, Canada, Germany, France, the United Kingdom, Italy, Spain, China, Japan, India, South Korea, Australia, Indonesia, Brazil, and Mexico
- Competitive profiles of leading public cloud providers with strategic landscape assessment
- Porter's Five Forces analysis, value chain insights, and assessment of industry challenges and opportunities
- Latest innovation trends covering AI-optimized infrastructure, edge computing and IoT integration, sovereign cloud offerings, industry-specific cloud solutions, and sustainable data center operations shaping market competition and customer adoption across key regional markets
Recent News and Developments in Public Cloud Market
-
July: Amazon Web Services, Microsoft Azure, and Google Cloud all reported accelerating quarterly growth. AWS revenue reached USD 42.2 Billion with USD 16.6 Billion in operating income, up 37%, Azure surpassed USD 100 Billion in annual revenue growing 43%, and Google Cloud revenue reached USD 24.8 Billion, up 82%, with all three signaling that demand continues to exceed available capacity.
-
January: AWS announced general availability of the AWS European Sovereign Cloud, with its first Region in Brandenburg, Germany, operated entirely by EU-based staff. Amazon plans to invest more than EUR 7.8 Billion in Germany, supporting an average of 2,800 full-time equivalent jobs annually, and plans expansion through new Local Zones in Belgium, the Netherlands, and Portugal.
-
December: Microsoft announced its largest-ever Asia investment of USD 17.5 Billion in India over four years to expand cloud and AI infrastructure, skilling programs, and sovereign-ready digital capabilities, coming after Amazon's plan to invest more than USD 35 Billion in India and Google's USD 15 Billion commitment.
-
October: Google announced a USD 15 Billion investment over five years to establish its first AI hub in India, located in Visakhapatnam, which will be one of the company's largest AI facilities globally and will include data center infrastructure.
-
April: TCS launched the Sovereign Secure Cloud, an India-focused cloud solution for government and public sector enterprises that keeps sensitive data within national borders through data centers in Mumbai and Hyderabad. The offering supports AI integration and was introduced alongside the DigiBOLT AI-driven low-code platform and a Cyber Defense Suite.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current global public cloud market size and what is its projected value?
- Which service segment holds the largest share in the global public cloud market?
- What are the key drivers of global public cloud market growth?
- Which region dominates the global public cloud market and why?
- How are AI workloads, sovereign cloud requirements, and edge computing integration reshaping product development and competitive strategies in the public cloud industry?
- Who are the top companies in the global public cloud market and what are their competitive strategies?
- What are the investment and market entry opportunities across SaaS, SME, BFSI, government, and industry-specific public cloud segments?
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104



Top comments (0)